PERSONAL FINANCE
Where Does My Salary Go? 10 Hidden Money Leaks Draining Your Salary in India
By Suran Mohan . October 01, 2026
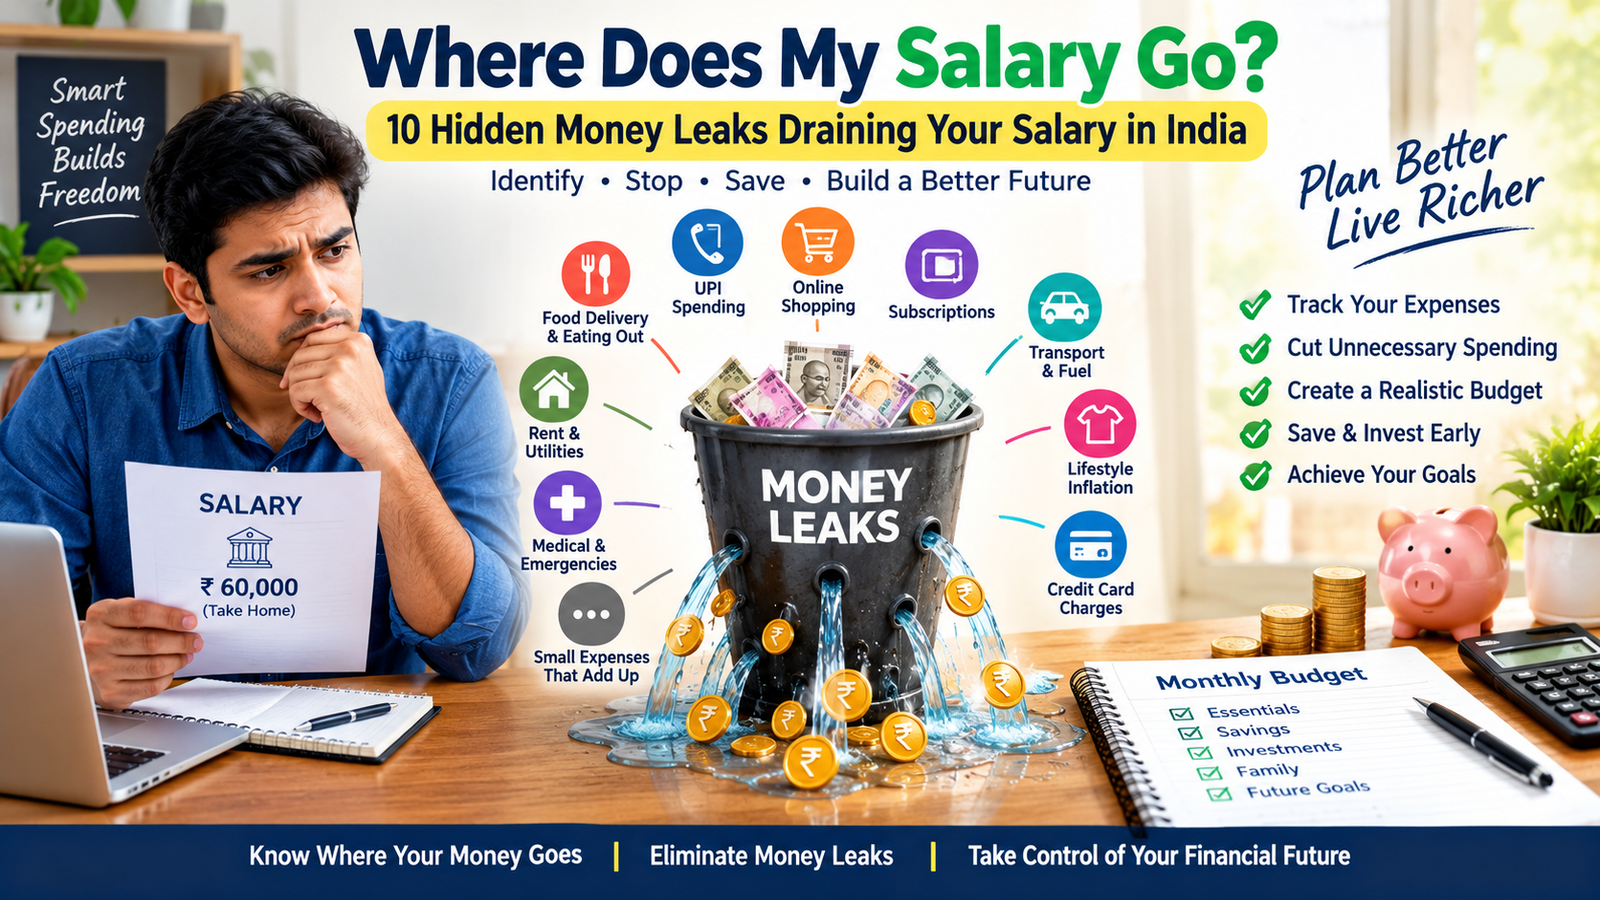
Have you ever received your salary, paid a few important bills, made a few UPI payments, ordered food a couple of times, purchased something online—and then suddenly wondered, “Where does my salary go?”
This is a common financial problem for salaried households in India. The issue is not always a large purchase. In many cases, our salary disappears through a collection of small, frequent expenses that feel insignificant individually but become substantial when added together.When we ask “where does my salary go every month?”, the answer is usually hidden across subscriptions, food delivery, convenience spending, online shopping, transport, impulse purchases, lifestyle upgrades, bank charges, and numerous small UPI transactions.The good news is that these money leaks can be identified, measured, and controlled without completely giving up the things we enjoy.
In This Article:
- Where Does My Salary Go Every Month?
- 10 Hidden Money Leaks Draining Your Salary
- Indian Salary Budget Example: How to Manage a ₹60,000 Monthly Salary
- Where Does the Remaining ₹5,000 Go?
- How Much Can We Save From a ₹60,000 Salary?
- How to Find Where Your Money Is Going
- A Simple Salary Leak Audit
- The 24-Hour Rule for Unnecessary Expenses
- How to Stop Your Salary From Disappearing Before Month-End
- Where Does My Salary Go? The Real Answer
- Final Thoughts: Make Every Rupee Have a Purpose
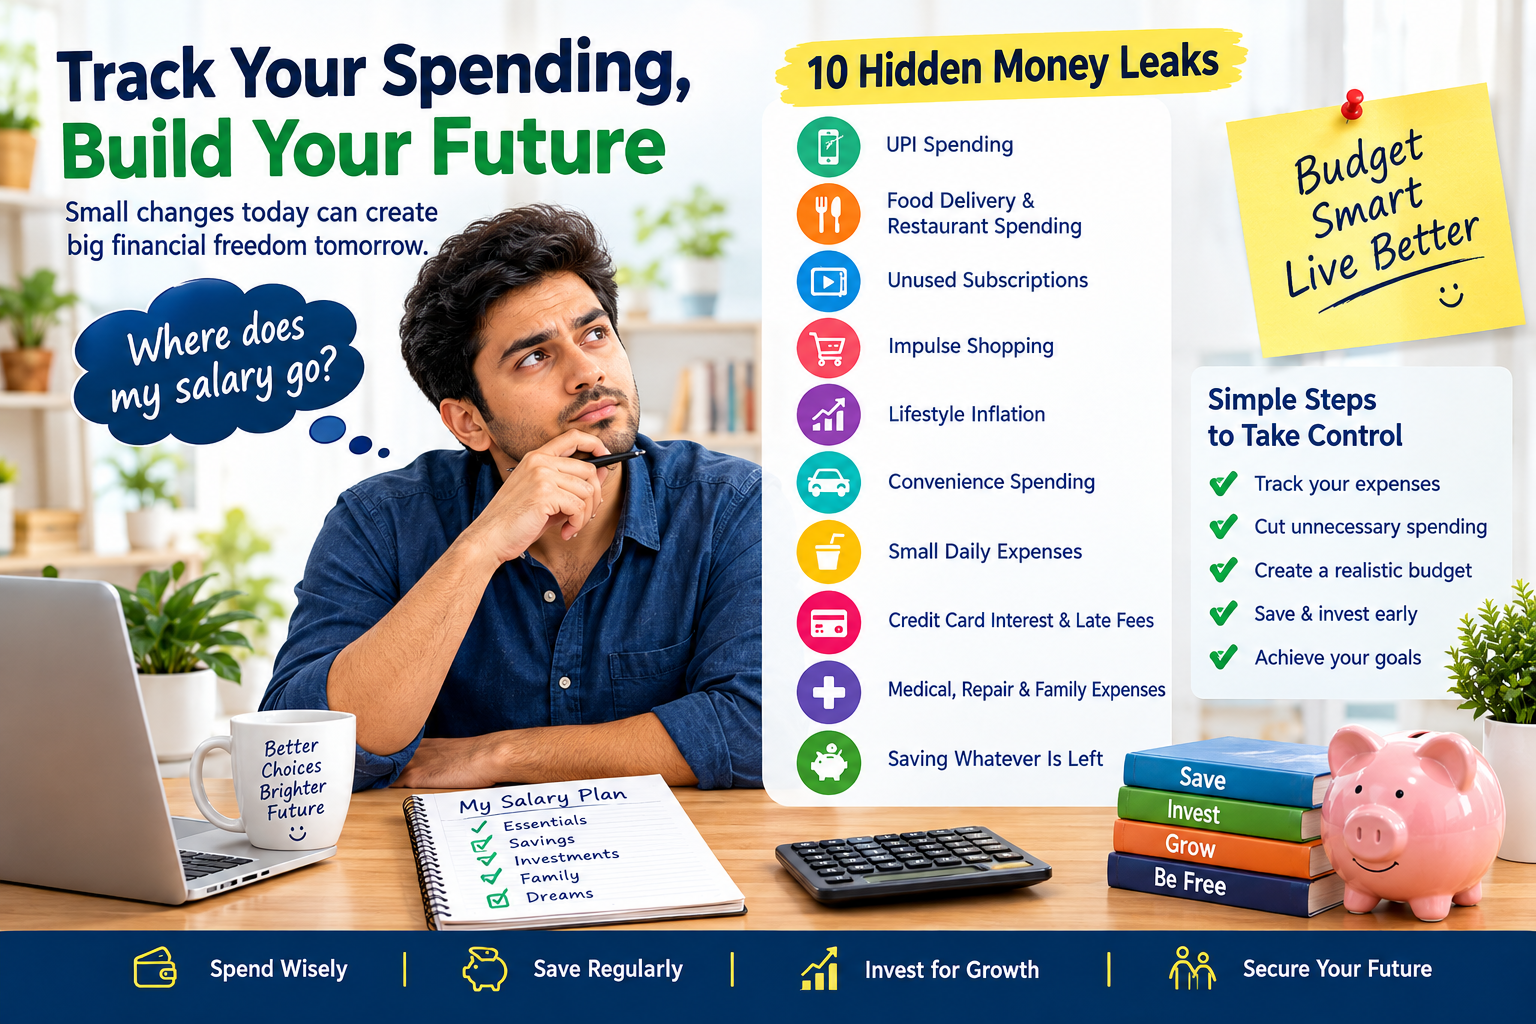
Where Does My Salary Go Every Month?
10 Hidden Money Leaks Draining Your Salary
1. Frequent UPI Spending
- ₹150 × 20 small transactions = ₹3,000
- ₹250 × 20 transactions = ₹5,000
- ₹300 × 25 transactions = ₹7,500
How to control UPI spending
- Essential
- Planned
- Convenience
- Impulse
- Unnecessary
2. Food Delivery and Restaurant Spending
3. Unused Subscriptions
4. Impulse Shopping and Online Purchases
- Flash sales
- Limited-time discounts
- “Only a few left” messages
- Free shipping thresholds
- Cashback offers
- Festival sales
- Buy-now-pay-later offers
- Social media recommendations
5. Lifestyle Inflation After a Salary Increase
- Savings
- Investments
- Debt repayment
- Lifestyle improvement
6. Convenience Spending
- Ordering groceries instead of planning a shopping trip
- Paying for frequent delivery
- Taking cabs for short distances
- Buying packaged snacks instead of carrying food
- Purchasing expensive coffee regularly
- Paying someone for tasks we could reasonably handle ourselves
7. Small Daily Expenses
8. Credit Card Interest and Late Fees
- Total outstanding balance
- Interest rate
- Minimum payment
- Due date
- Total interest being charged.
- Number of active credit accounts
9. Unplanned Medical, Repair and Family Expenses
- Medical bills
- Vehicle repairs
- Home repairs
- School-related expenses
- Family functions
- Travel emergencies
- Appliance replacement
- Annual insurance premiums
10. Saving Whatever Is Left at Month-End
- Essential household expenses
- Emergency fund
- Investments
- Insurance
- Debt repayment
- Personal spending
- Family activities
How to Find Where Your Money Is Going
| Expense | Amount | Category | Necessary? |
| Groceries | ₹4,500 | Essential | Yes |
| Food delivery | ₹1,800 | Lifestyle | No |
| Electricity | ₹2,000 | Essential | Yes |
| Online shopping | ₹2,400 | Discretionary | No |
| Transportation | ₹2,500 | Essential | Mostly |
| Subscriptions | ₹900 | Recurring | Review |
A Simple Salary Leak Audit
1. What did we buy that we did not plan to buy?
2. Which recurring payments are no longer useful?
3. Which expenses increased compared with last month?
4. Which small expenses occurred repeatedly?
5. How much did we save before spending?
The 24-Hour Rule for Unnecessary Expenses
- Do we actually need it?
- Do we already own something similar?
- Was this purchase planned?
- Can we afford it without affecting our financial goals?
- Would we still buy it without a discount?
- Is the purchase worth the number of hours we worked to earn its cost?
How to Stop Your Salary From Disappearing Before Month-End
Step 1: Know Our Take-Home Salary
Step 2: List Fixed Expenses
Step 3: Estimate Variable Expenses
Step 4: Set Savings Before the Month Begins
Step 5: Create a Discretionary Spending Limit
Step 6: Track Every Small Payment
Step 7: Conduct a Weekly Review
Where Does My Salary Go? The Real Answer
Final Thoughts: Make Every Rupee Have a Purpose
Key Takeaways
- Know your total monthly income.
- Track your essential and non-essential expenses.
- Set realistic savings goals.
- Review your budget regularly.
- Adjust your plan when your circumstances change.
FAQ Section
What is the purpose of a monthly budget?
Answer in a short paragraph.
How much money should I save every month?
Answer carefully and avoid presenting one universal percentage as appropriate for everyone.
How often should I review my budget?
Give a practical answer.
Conclusion: Take Control of Where Your Salary Goes
If we often ask “where does my salary go every month?”, the answer is usually not one large expense. Our income can gradually disappear through UPI spending, food delivery, subscriptions, impulse shopping, convenience expenses, lifestyle inflation, credit-card costs and numerous small purchases that seem insignificant individually but become substantial over time.
The first step is to make these money leaks visible. By reviewing bank statements, UPI transactions, credit-card bills and recurring subscriptions, we can understand exactly where our money is going. A practical monthly salary budget then helps us separate essential expenses from discretionary spending and financial priorities.
For example, a ₹60,000 monthly salary can be organised into household needs, savings, investments, family requirements, personal spending and an emergency buffer. The exact amounts should reflect our income, location, family responsibilities and financial goals.
Most importantly, we should avoid the habit of saving whatever is left at the end of the month. Instead, we can decide our savings and investment amount in advance and then manage our spending around that target.
We do not need to eliminate every enjoyable expense. We need to ensure that our spending is intentional and aligned with what matters most to us.
Track every rupee. Identify the leaks. Control unnecessary expenses. Save consistently. Invest for the future.
When we know where our salary goes, we can make every rupee work toward a more secure and financially independent future.