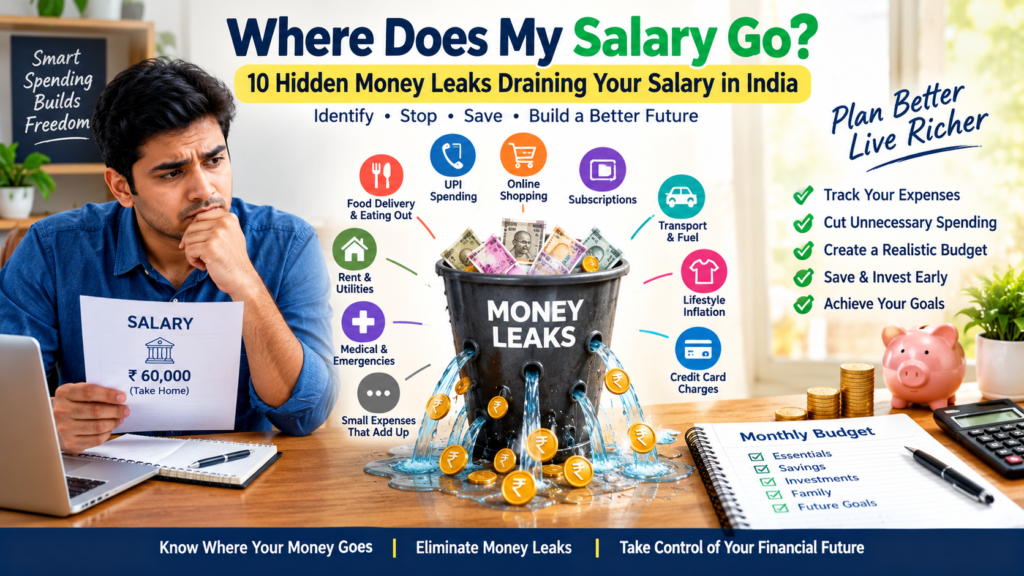
Where Does My Salary Go? 10 Hidden Money Leaks Draining Your Salary in India
PERSONAL FINANCE Where Does My Salary Go? 10 Hidden Money Leaks Draining Your Salary in India By Suran Mohan . October 01, 2026 Have you ever received your salary, paid a few important bills, made a few UPI payments, ordered food a couple of times, purchased something online—and then suddenly wondered, “Where does my salary go?” This is a common financial problem for salaried households in India. The issue is not always a large purchase. In many cases, our salary disappears through a collection of small, frequent expenses that feel insignificant individually but become substantial when added together.When we ask “where does my salary go every month?”, the answer is usually hidden across subscriptions, food delivery, convenience spending, online shopping, transport, impulse purchases, lifestyle upgrades, bank charges, and numerous small UPI transactions.The good news is that these money leaks can be identified, measured, and controlled without completely giving up the things we enjoy. In This Article: Where Does My Salary Go Every Month? 10 Hidden Money Leaks Draining Your Salary Indian Salary Budget Example: How to Manage a ₹60,000 Monthly Salary Where Does the Remaining ₹5,000 Go? How Much Can We Save From a ₹60,000 Salary? How to Find Where Your Money Is Going A Simple Salary Leak Audit The 24-Hour Rule for Unnecessary Expenses How to Stop Your Salary From Disappearing Before Month-End Where Does My Salary Go? The Real Answer Final Thoughts: Make Every Rupee Have a Purpose Where Does My Salary Go Every Month? Our salary generally moves through several stages during the month:Salary received → essential expenses → lifestyle spending → debt/EMIs → small purchases → unexpected expenses → savings, if anything remains.The problem occurs when savings are treated as whatever is left at the end of the month.If we spend first and save later, there may be very little left to save. A better approach is to treat savings as a planned monthly expense.For example, if our take-home salary is ₹60,000, we should decide in advance how much will go toward household expenses, insurance, investments, emergency savings, debt repayment, and discretionary spending.Without a plan, even ₹60,000 can disappear surprisingly quickly. 10 Hidden Money Leaks Draining Your Salary 1. Frequent UPI Spending UPI has made payments extremely convenient. We can pay for tea, snacks, groceries, transportation, food delivery, and online purchases within seconds.The convenience is useful, but it can also make spending less visible.A ₹150 payment may not feel important. Neither does ₹280, ₹190, or ₹350. However, dozens of such transactions can create a significant monthly expense.For example: ₹150 × 20 small transactions = ₹3,000 ₹250 × 20 transactions = ₹5,000 ₹300 × 25 transactions = ₹7,500 This is one reason we may wonder why our salary disappears even though we cannot remember making a major purchase. How to control UPI spending At the end of every week, review UPI transactions and classify them into: Essential Planned Convenience Impulse Unnecessary The objective is not to stop using UPI. It is to make invisible spending visible. 2. Food Delivery and Restaurant Spending Food is an essential expense, but convenience food can become a major hidden expense.Ordering a ₹250 meal may appear affordable. But the final bill can include delivery charges, platform fees, taxes, beverages, desserts, and additional items.Suppose we order food twice a week and spend an average of ₹500 per order.That becomes approximately:₹500 × 8 orders = ₹4,000 per month.Over a year, that is ₹48,000.If restaurant visits, snacks, and coffee are added, the total can become considerably higher.We can reduce this money leak by deciding beforehand how many restaurant or food-delivery occasions we will have each month. 3. Unused Subscriptions Streaming platforms, music applications, cloud storage, premium apps, fitness memberships, and other subscriptions can quietly consume our salary.The problem is particularly significant when we subscribe to something for a specific purpose and then stop using it.For example, five subscriptions costing an average of ₹300 each represent:₹300 × 5 = ₹1,500 per month.That is ₹18,000 per year.The solution is simple: review every recurring payment once every three months.For each subscription, ask:“Did we use this enough during the last 30 days to justify paying for it?”If the answer is no, cancellation can immediately stop that money leak. 4. Impulse Shopping and Online Purchases Online shopping has made purchasing extremely easy. A product can move from our wish list to our doorstep with just a few clicks.The problem is not necessarily expensive shopping. Small expenses that add up can have a greater cumulative impact.A ₹700 purchase may not disturb our budget. Ten such purchases can create a ₹7,000 expense.Common triggers include: Flash sales Limited-time discounts “Only a few left” messages Free shipping thresholds Cashback offers Festival sales Buy-now-pay-later offers Social media recommendations A discount does not create savings if we would not have purchased the item without the discount.Before buying, we can apply a 24-hour waiting rule for non-essential purchases. For expensive purchases, extending the waiting period to 7 or even 30 days can provide greater clarity. 5. Lifestyle Inflation After a Salary Increase A salary increase should ideally improve our financial position. However, our expenses often increase along with our income.This is called lifestyle inflation.For example, after receiving a ₹10,000 monthly salary increase, we might upgrade our phone, eat out more often, increase online shopping, and take more expensive vacations.Eventually, the additional income disappears into additional expenses.Instead, we can divide every salary increase between: Savings Investments Debt repayment Lifestyle improvement For example, if our salary increases by ₹10,000, we could decide that ₹6,000 goes toward financial goals while ₹4,000 improves our lifestyle.This allows us to enjoy higher income without allowing our entire financial life to expand with it. 6. Convenience Spending Convenience is valuable, but convenience also has a price.Examples include: Ordering groceries instead of planning a shopping trip Paying for frequent delivery Taking cabs for short distances Buying packaged snacks instead of carrying food Purchasing expensive coffee regularly Paying someone for tasks we could reasonably handle ourselves None of
Where Does My Salary Go? 10 Hidden Money Leaks Draining Your Salary in India Read More »